What is the overall scope and trajectory of the Steel Ball Market?
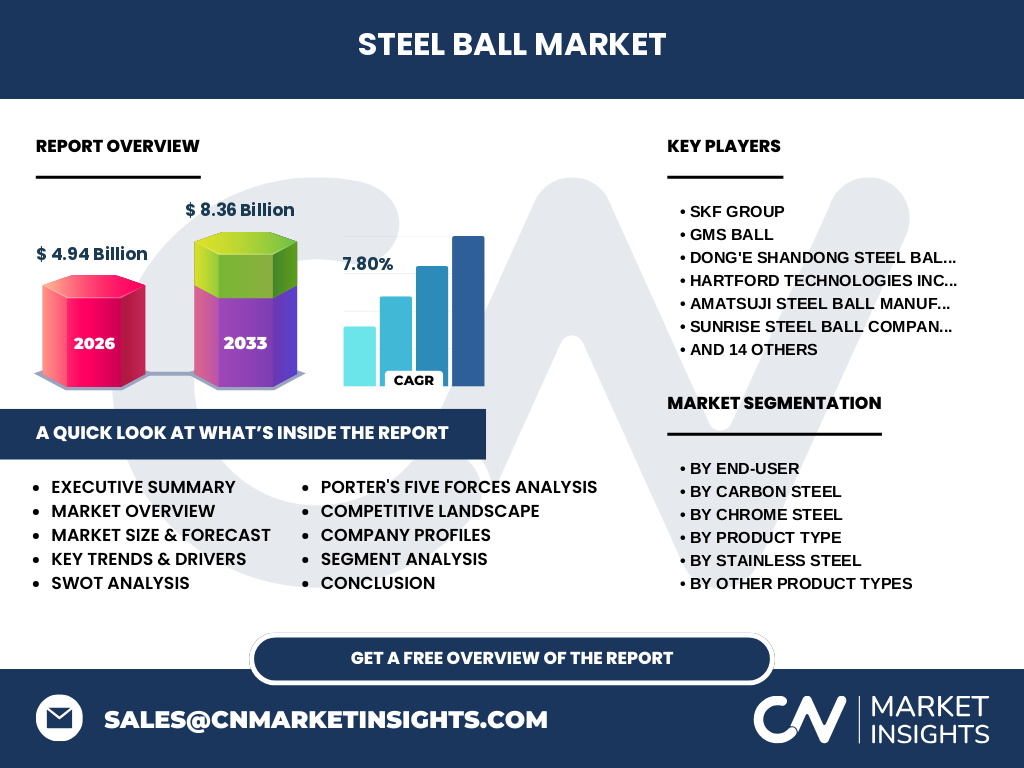
Our analysis indicates the Steel Ball Market size stands at $4.94 Billion in 2026, driven by fundamental applications in heavy machinery, automotive powertrains, and aerospace bearings. This foundational sector underpins global mechanical motion control.
Structural Growth Drivers and Market Restraints
The market is propelled by a robust 7.80% CAGR, reaching $8.36 Billion by 2033. Raw material price volatility in high-grade steel alloys acts as a primary operational restraint, forcing manufacturers to optimize their supply chain logistics.
Emerging Trends and Growth Patterns in Precision Manufacturing
The shift toward lightweight engineering has accelerated demand for advanced Ceramic Steel Balls and high-grade Chrome Steel variants. Industry leaders are heavily investing in automated surface defect detection to meet stringent ISO quality benchmarks.
How did the global pandemic impact the sector's recovery trajectory?
Supply chain disruptions during COVID-19 exposed severe vulnerabilities in cross-border component sourcing. The post-pandemic recovery trajectory reflects a strategic pivot toward regional warehousing and nearshoring among top-tier tier suppliers.
Competitive Benchmarking and Industry Consolidation
The market features high competitive concentration, anchored by major players like SKF Group, Amatsuji Steel Ball Manufacturing Company Limited, and Hartford Technologies Inc. These firms leverage advanced heat-treatment technologies to secure dominant OEM supply contracts.
Executive Summary of the Steel Ball Market Analysis
Our comprehensive research underscores a market primed for high-value expansion, projecting valuation to surge from $4.94 Billion in 2026 to $8.36 Billion by 2033. Strategic focus on specialized alloy production remains critical for profitability.
Long-Term Market Forecast and Valuation Projections
Propelled by accelerated industrial automation, the Steel Ball Market industry trends point to sustained momentum, achieving a projected valuation of $8.36 Billion by 2033 at a steady 7.80% CAGR from its $4.94 Billion baseline in 2026.
Granular Segmentation Analysis Across End-Users and Materials
Market segmentation spans critical end-users including Automotive, Industrial, Aerospace, and Mining, alongside material categories like Chrome Steel, Stainless Steel, and Carbon Steel. Each segment dictates specific metallurgical requirements for load capacity and corrosion resistance.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights robust manufacturing hubs across Asia-Pacific, North America, and Europe. Industrial clusters in these zones dictate localized demand for specialized ball bearings deployed in heavy wind turbines and automotive transmissions.
In-Depth Regional Review of High-Growth Industrial Zones
Asia-Pacific dominates consumption volume due to dense automotive manufacturing bases, while North America and Europe prioritize high-margin aerospace and medical-grade stainless steel components. Regional regulatory compliance significantly shapes local supplier ecosystems.
Strategic Positioning of Leading Company Profiles
Industry stalwarts like Dong'e Shandong Steel Ball Group Company Limited, Global Precision Ball & Roller Inc., and Abbott Ball Company Inc. maintain competitive edges through proprietary forging techniques and vast global distribution networks.
Porter's Five Forces Assessment of Competitive Pressures
Bargaining power of raw material suppliers remains moderate-to-high, while threat of substitutes is mitigated by the unmatched durability of Chrome Steel and Ceramic Steel Balls in high-stress operational environments.
SWOT Analysis of the Global Steel Ball Ecosystem
Strengths lie in advanced metallurgical expertise; weaknesses involve high capital expenditure for precision grinding machinery. Opportunities abound in emerging renewable energy sectors, whereas threats stem from fluctuating nickel and chromium tariffs.
Value Chain Analysis from Raw Metallurgy to End-User Delivery
The value flow originates from raw wire rod procurement, progressing through cold heading, flash grinding, heat treatment, and lapping. Quality assurance protocols at each step dictate whether output satisfies automotive or aerospace standards.
Investment Insights and High-Potential Opportunity Areas
Investors should target niche manufacturers producing Tungsten Carbide Balls and specialized Austenitic Stainless Steel components, as these high-margin segments outperform commoditized carbon steel variants in growth potential.
Conclusion and Strategic Industry Takeaways
Capturing future growth in this $8.36 Billion market by 2033 requires continuous R&D investment in friction-reduction technologies and supply chain resilience against geopolitical trade friction.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with c-suite executives, and macroeconomic industrial output indicators to ensure absolute data integrity.
Scope of the Report and Analytical Coverage Parameters
This report encompasses a global evaluation of the Steel Ball Market analysis, covering products ranging from carbon steel to brass balls across direct sales and online retail channels, excluding unverified artisanal workshops.
Recent Developments, Partnerships, and Corporate Strategic Moves
Recent industry momentum features aggressive capacity expansions by companies like RGPBALLS Società a Responsabilità Limitata and Kwality Ball Private Limited, focusing on eco-friendly manufacturing processes and localized distribution hubs.